
Global Military Spending Hit $2.89 Trillion in 2025, Led by Record European Rearmament
Global military spending climbed to $2.887 trillion in 2025, rising for the 11th straight year despite a significant U.S. drawdown, according to new data published April 27 by the Stockholm International Peace Research Institute (SIPRI). The annual increase of 2.9% was considerably smaller than the 9.7% jump recorded in 2024, but that moderation is almost entirely explained by the drop in U.S. spending — outside the United States, global outlays grew by 9.2%.
- Global military expenditure reached $2.887 trillion in 2025 — the 11th consecutive annual rise — pushing the global military burden to 2.5% of GDP, the highest since 2009.
- U.S. military spending fell 7.5% to $954 billion, primarily because the Trump administration approved no new financial military aid for Ukraine — a sharp reversal from the $127 billion committed over the prior three years.
- European NATO members collectively spent $559 billion, with 22 of 29 members hitting the 2% GDP threshold. Germany surpassed 2% for the first time since 1990; Spain crossed it for the first time since 1994.
- China increased military spending 7.4% to $336 billion — its 31st consecutive annual rise — while Taiwan surged 14% to $18.2 billion amid intensifying PLA exercises.
- U.S. Congress has approved defense funding of over $1 trillion for 2026, with a Trump budget proposal that could push spending to $1.5 trillion by 2027.
The report positions 2025 as a structural inflection point: Washington’s pullback was policy-driven and almost certainly temporary, while Europe’s acceleration reflects a generational shift in how the continent approaches collective defense.
The Big Picture
The world is rearming at a pace unseen since the Cold War’s final decade. Persistent conflict in Ukraine, expanding Chinese military power in the Indo-Pacific, and the Trump administration’s transactional approach to alliance commitments have collectively forced governments across Europe, Asia, and beyond to recalibrate their defense postures.
SIPRI researcher Xiao Liang summarized it plainly: “Global military spending rose again in 2025 as states responded to another year of wars, uncertainty and geopolitical upheaval with large-scale armament drives.” The institute projects that growth will persist through 2026 and beyond, given the breadth and depth of ongoing rearmament programs.
The global military burden now stands at 2.5% of GDP — its highest level since 2009 — a milestone that reflects not just rising nominal expenditures but genuine structural prioritization of defense across dozens of governments simultaneously.
What’s Happening
The United States, China, and Russia combined for $1.48 trillion in military outlays, accounting for 51% of all global defense spending. But the composition of that dominance is shifting in ways that carry long-term implications.
United States: U.S. military spending fell to $954 billion in 2025, primarily because no new financial military assistance for Ukraine was approved. Over the previous three years, Washington had committed $127 billion to Kyiv. Critically, the Pentagon continued investing in nuclear modernization and conventional force improvements targeting the Indo-Pacific, meaning the reduction did not reflect declining core military capacity.
Europe: European military spending rose 14% to $864 billion — the largest single regional driver of global spending growth. Spending by Russia and Ukraine each continued to climb in the fourth year of the war, while European NATO members recorded the sharpest annual spending growth since the Cold War ended.
Germany led European NATO spenders at $114 billion, a 24% year-on-year increase, crossing the 2% of GDP threshold for the first time since 1990. Spain surged 50% to $40.2 billion, also clearing the 2% threshold for the first time since 1994.
Ukraine and Russia: Ukraine, the seventh largest military spender in 2025, increased outlays by 20% to $84.1 billion — equivalent to 40% of GDP. Russia’s spending grew 5.9% to $190 billion, representing 7.5% of GDP. Both countries reached the highest share of government spending ever recorded for their respective militaries.
Asia and Oceania: The region registered 8.1% spending growth to $681 billion — the fastest annual rise since 2009. China’s $336 billion represented a 7.4% increase and its 31st consecutive year-on-year climb. Japan reached $62.2 billion (1.4% of GDP, highest since 1958), and Taiwan surged 14% to $18.2 billion, its largest single-year increase in at least three decades.
Why It Matters
The 2025 data confirms that the post-Cold War “peace dividend” era is definitively over. Defense budgets are no longer calibrated to peacetime baselines; they are being sized against active wars, near-peer competitors, and the erosion of arms control frameworks.
For the U.S. defense industrial base, the data is actually bullish. SIPRI’s Program Director Nan Tian stated: “The decline in US military expenditure in 2025 is likely to be short-lived. Spending approved by the US Congress for 2026 has risen to over $1 trillion, a substantial increase from 2025, and could rise further to $1.5 trillion in 2027 if President Trump’s latest budget proposal is accepted.”
That trajectory — from $954 billion in 2025 to a potential $1.5 trillion by 2027 — would represent one of the fastest two-year increases in U.S. defense outlays in history. For prime contractors and second-tier suppliers, the production ramp-up implications are significant, touching everything from munitions stockpiling to shipbuilding to advanced fighter procurement.
Strategic Implications
The structural meaning of Europe’s 14% spending surge runs deeper than headline budget numbers. SIPRI researcher Jade Guiberteau Ricard noted that “in 2025 military spending by European NATO members rose faster than at any time since 1953, reflecting the ongoing pursuit of European self-reliance alongside increasing pressure from the United States to strengthen burden sharing within the alliance.”
This dual dynamic — the European Union developing independent defense capacity while simultaneously satisfying NATO burden-sharing demands — marks a geopolitical shift that will define transatlantic relations for the next decade. Europe is no longer free-riding; it is building sovereign capability that may reduce its strategic dependence on Washington over time.
The acceleration of Asia-Pacific spending carries equally profound implications. SIPRI Senior Researcher Diego Lopes da Silva assessed that U.S. allies in Asia “are spending more on their militaries, not only due to long-standing regional tensions but also due to growing uncertainty over US support.” Japan, Australia, the Philippines, and Taiwan are each hedging against the possibility of reduced American commitment in a future crisis — a calculus driven directly by the Trump administration’s unpredictability on alliance commitments.
Competitor View
Beijing will read the SIPRI data through two distinct lenses. China’s own 31-year consecutive spending increase — now at $336 billion — continues to validate its military modernization strategy. At the same time, Taiwan’s 14% surge and Japan’s accelerating rearmament confirm a regional balancing dynamic that the PLA must factor into its operational planning, particularly regarding any cross-strait contingency timeline.
Moscow’s position is paradoxical. Russia sustains a war economy at 7.5% of GDP, but its military burden is approaching fiscal stress points. SIPRI researcher Lorenzo Scarazzato noted that “spending is likely to keep growing in 2026 if the war continues, with revenues from Russia’s oil sales increasing and a major European Union loan expected by Ukraine.” A prolonged war sustains Russia’s advantage in absorbing attrition, but the European spending surge is beginning to close the long-term capability gap that Moscow relied upon.
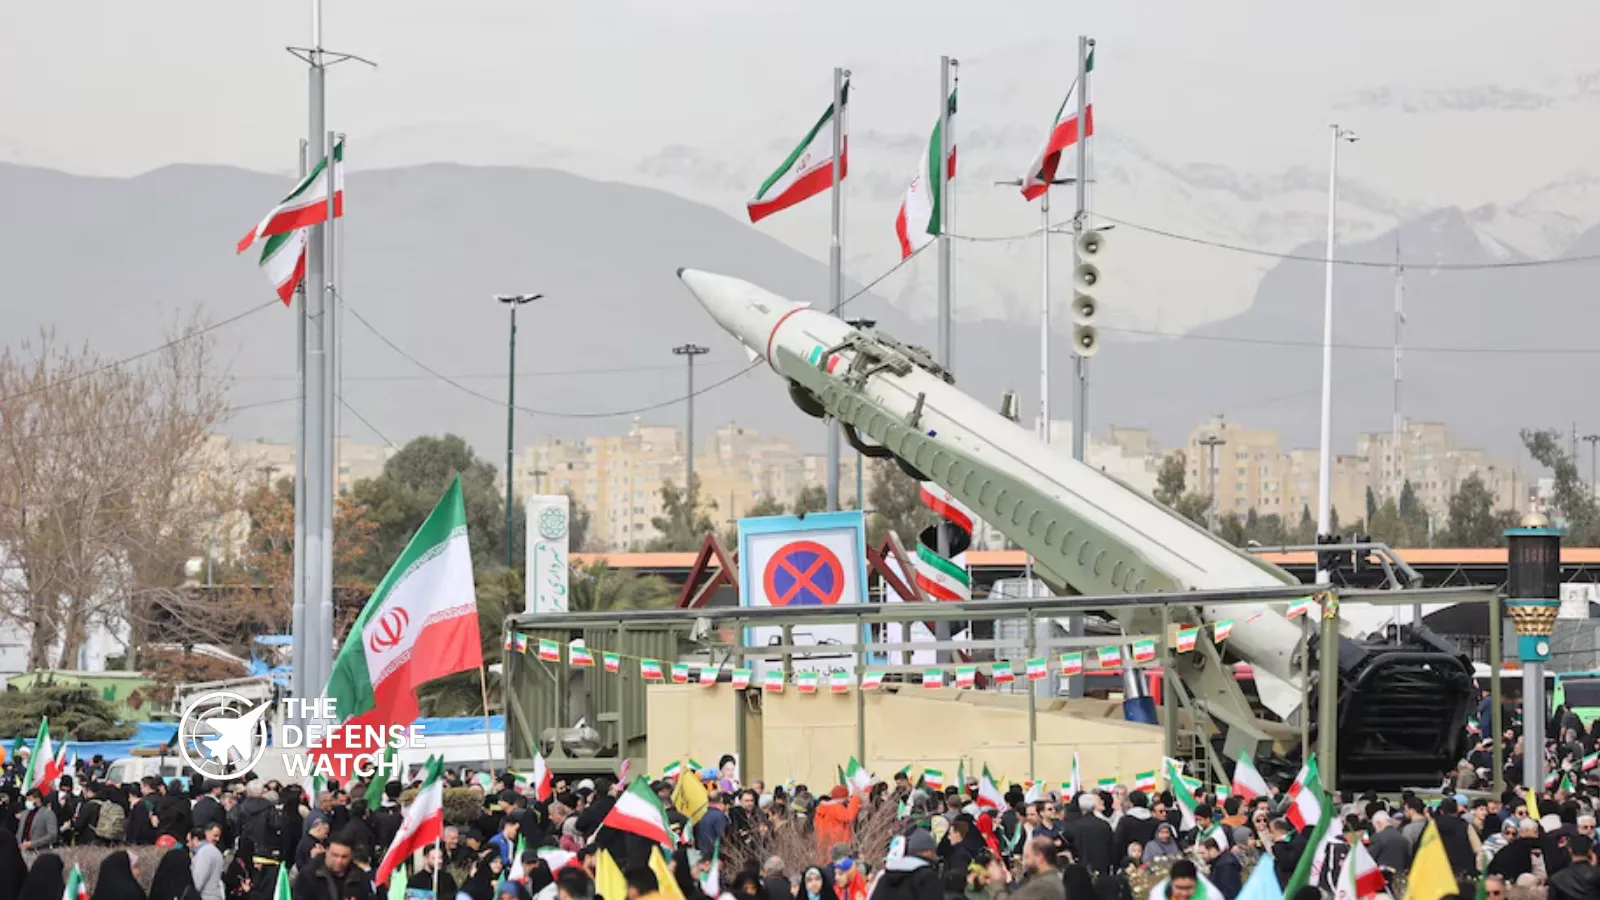
Iran presents a different picture. Despite ongoing regional conflicts, Iran’s spending fell 5.6% in real terms to $7.4 billion due to 42% annual inflation, though SIPRI noted that official figures “almost certainly understate the true level of Iran’s spending,” as Tehran uses off-budget oil revenues to fund missile and drone programs. The regime’s actual military investment in asymmetric tools — drones, precision missiles, proxy forces — substantially exceeds what any budget figure captures.
What To Watch Next
Several near-term developments will determine how the 2025 data translates into actual capability.
The U.S. fiscal year 2026 defense budget — already authorized above $1 trillion — enters execution. Watch for supplemental requests and whether the Trump administration’s proposed $1.5 trillion FY2027 figure survives Congressional negotiation.
Within NATO, the alliance adopted new spending targets in 2025. SIPRI cautioned that “as states strive to meet the new NATO spending targets, there is a risk that the boundaries between military and other ‘defence- and security-related’ expenditures become blurred, reducing transparency and further complicating the assessment of military capabilities.” That warning deserves close attention: inflated headline figures that include civilian infrastructure spending could mask genuine readiness gaps.
In Asia, Taiwan’s procurement pipeline — funded by that 14% spending surge — will be monitored closely by both the Pentagon and the PLA. Japan’s multi-year defense buildup, targeting 2% of GDP, continues to accelerate with new strike capability acquisitions.
Capability Gap
The most operationally consequential gap exposed by the 2025 data is in European munitions production capacity. European governments committed more money in 2025, but the defense industrial base — particularly artillery shell, air defense interceptor, and armored vehicle production — has not yet scaled to meet wartime demand levels. Budget increases take 18 to 36 months to translate into deliverable hardware.
Germany’s 24% spending increase and Spain’s 50% surge reflect political will; they do not yet reflect fielded capability. The gap between authorized budgets and operational readiness remains the central challenge for NATO’s eastern flank.
On the U.S. side, the 7.5% spending reduction in 2025 was largely isolated to Ukraine aid transfers — it did not reduce core readiness funding. However, any multi-year pause in allied resupply creates inventory depletion risks that the 2026 and 2027 budgets must address.
The Bottom Line
The 2025 SIPRI data confirms that the world has entered a sustained global rearmament cycle — one in which U.S. spending is set to surge past $1 trillion, Europe is investing at Cold War-era intensity, and China’s military expansion shows no signs of plateauing, making the structural drivers of global defense spending growth more durable than at any point in the post-Cold War era.